Service
Card Processing
Taking card payments is the plumbing under every business's front counter: the terminal the customer taps, the network behind it, and the account the money lands in. This page is what that actually involves, written for someone who has to run it rather than sell it.
Zero Cost Equipment And 0% Fees With Cash Discount
Mon–Sat, 9am–5pm · Or send the form at the bottom of this page and we will reply within one business day.
01
Getting Set Up To Accept Cards
Setting up card acceptance starts with a short application rather than a long project. We need to know what your business is, roughly how you take money today, and who the owners are. That is what the application asks for, and it is usually turned around quickly rather than sitting in a queue.
While that is happening, the more useful conversation is about your counter. How many people take payment at once? Is there one till or three? Do customers pay where they stand, or at a register by the door? Those answers decide the hardware long before anyone talks about a brand.
You will see the terms in writing before anything is installed, and we walk through them with you in plain language. Nothing about your agreement should be a surprise six months in — that is the standard we hold ourselves to, and it applies whether you are taking cards for the first time or moving from a provider you already have.
- A short application, not a long project
- Equipment chosen around your counter, not around a brand
- Terms explained in writing before anything is installed
02
The Equipment That Comes With It
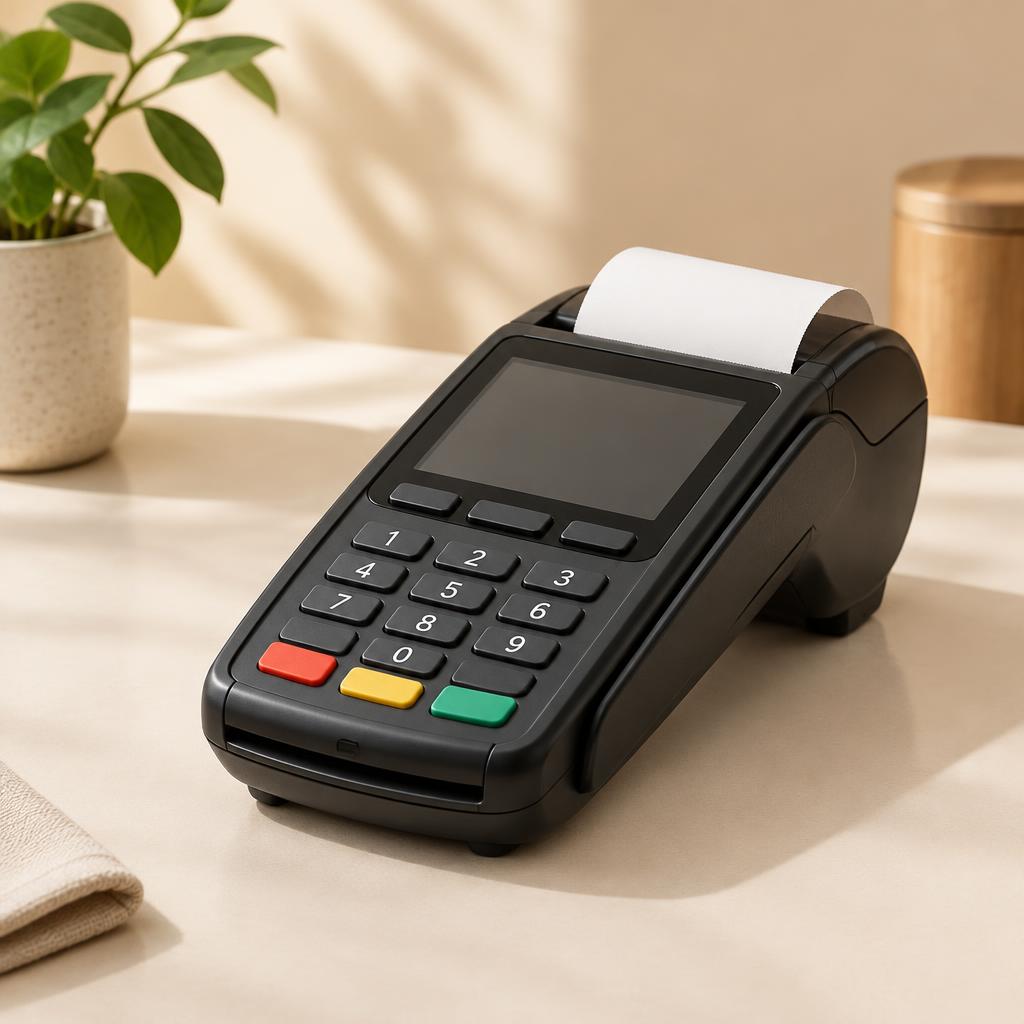
There is no single terminal that suits every counter. A café with one busy till and a hardware store with a checkout line and a service desk need different things. The range runs from a reader that pairs with a phone to a full station with a receipt printer and a customer-facing display on the other side of the counter.
Beyond the terminal there is usually something else doing the work: a register or a screen for ringing up the sale, a handheld for taking payment away from the till, or a kitchen display if the orders come off a line. We set up whichever combination fits, and if something your business needs is not in the usual range, we go and find it.
On the money side of the hardware: equipment is zero cost with a business account. The conversation on a setup call is about what fits your counter, not about a price.
03
What A Card Payment Costs, And Why
A card payment is not one charge. It is several, and understanding the shape of them is what makes a statement readable rather than mysterious.
Part of the cost goes to the card networks and the banks that issued the card. That part is set by them, and no processor controls it. On top of it sits the processor's own margin, plus whatever monthly and per-statement charges a provider applies, and often a separate cost for a card that is not present — an order taken over the phone or online rather than tapped at the counter.
So when you compare one provider with another, the number that matters is what you would actually pay on a month that looks like your real month, with every charge included. Not a headline rate.
That is exactly why we lead with Cash Discount rather than a rate: with the program, your card processing fees come to 0% instead of a percentage of every sale. If you want to talk through how that works against the numbers on your own statement, that is a conversation rather than something to put on a page.
- A card payment is several charges, not one
- Some of it is set by the banks, and some of it is the provider's own
- Compare on a real month, all charges included — not on a headline rate
04
Where The Money Lands, And When
A sale does not go straight into your bank account. Throughout the day the day's card payments are batched, and that batch is settled after your daily cutoff time. Batches that close before the cutoff normally fund the next business day. Batches that close over a weekend or a holiday fund on the next banking day.
Two things are worth knowing up front, because they are the ones that catch owners out. The first is your cutoff time — it is usually earlier than people assume, and a payment taken at 6pm may belong to the following day. The second is how weekends are handled, because a restaurant or a shop that does most of its trade on a Saturday should know when that money arrives.
We confirm your cutoff when we set you up, and we will walk you through what a normal week of funding will look like for your business, so there are no surprises in the first month. For most independent businesses cash flow matters at least as much as the cost, and the two should be looked at together.
05
Support When Something Goes Wrong
The test of a payment provider is not how it behaves on a quiet Tuesday morning. It is what happens on a busy Saturday when a terminal stops responding and there is a line.
The single most useful thing you can ask any provider — including us — is who answers, how quickly, and whether it is the same people each time. A support line that hands you to a new name every call is worse than a slightly slower one where somebody already knows your setup.
On our side, you reach a person Monday through Saturday, nine to five, on the same number you called on day one. Not a ticket number, and not a queue with a hold message. When something goes sideways at the counter, that is the difference between a fifteen-minute problem and a lost afternoon of trade.
- One number from day one, answered by a person
- Reachable Monday through Saturday, 9am to 5pm
- Somebody who already knows your setup
Next step
Talk it through with us.
Call, text or send the form. Tell us what your business uses today and what you would like to change, and we will tell you honestly what we can do. There is no obligation to go further, and no pressure either way.
Mon–Sat, 9am–5pm · support@minervapays.com
Run a restaurant instead? Read our guide to point of sale and card processing for restaurants.